Trading One Dependency for Three: The Hidden Vulnerabilities Inside America's China Decoupling Strategy
For the better part of a decade, reducing exposure to Chinese supply chains has been treated as an unambiguous strategic imperative inside American boardrooms. The logic appeared sound: a single-country concentration of this magnitude, in a nation whose geopolitical relationship with the United States continues to deteriorate, represented an unacceptable risk. The prescription seemed equally clear—diversify, reshore, nearshore, and redistribute.
What that prescription failed to account for was the quality of the alternatives.
As capital, production capacity, and sourcing relationships migrate away from China, they are not dispersing into a stable, well-distributed global landscape. They are concentrating—often heavily—in a small cluster of emerging markets that carry their own distinct and underappreciated risk profiles. The decoupling movement, in its urgency to solve one problem, has methodically created several others.
The Illusion of Diversification
Diversification is one of the foundational principles of risk management. Its value, however, depends entirely on the independence of the exposures being created. When companies move manufacturing from Shenzhen to Ho Chi Minh City, from Guangzhou to Chennai, or from Shanghai to Monterrey, they are not necessarily escaping concentrated risk. In many cases, they are exchanging a known, well-mapped concentration for a poorly understood one.
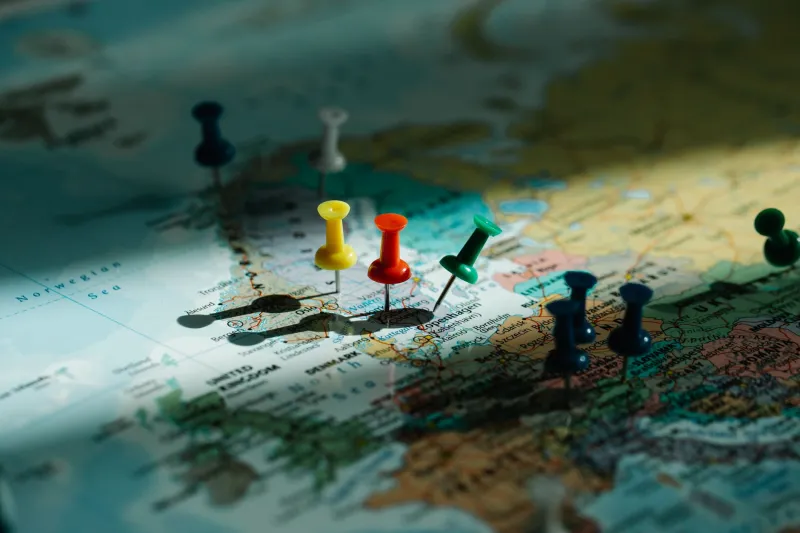
Vietnam, for instance, has absorbed an extraordinary volume of manufacturing investment over the past several years. Electronics assembly, apparel, and component manufacturing have all shifted there in significant quantities. What receives far less attention is Vietnam's own strategic dependency on China—for raw materials, for intermediate goods, and for the infrastructure of its export economy. A serious deterioration in Sino-Vietnamese relations, or a Chinese decision to restrict inputs flowing southward, would send cascading disruptions through the supply chains American companies believe they have insulated from Beijing's influence.
The geography of decoupling, examined carefully, reveals a pattern of substitution rather than genuine risk reduction.
India's Promise and Its Complications
India occupies a particularly prominent position in the American corporate imagination as a China alternative. Its democratic governance, English-language infrastructure, and vast labor pool make it an appealing destination for both manufacturing relocation and technology services expansion. The strategic alignment between Washington and New Delhi adds a layer of political comfort that executives find reassuring.
That comfort deserves scrutiny. India maintains what its own officials describe as a policy of strategic autonomy—a deliberate refusal to align exclusively with any single great power. In practice, this means New Delhi continues to deepen its energy relationship with Russia, maintains significant defense procurement ties with Moscow, and conducts its own independent foreign policy calculus that does not automatically track American interests. Companies treating India as a geopolitically neutral alternative to China are projecting a stability and alignment that the actual strategic landscape does not support.
Beyond the geopolitical dimension, India's domestic operating environment introduces friction that is frequently underestimated during investment planning. Regulatory inconsistency across state governments, infrastructure gaps that vary dramatically by region, and a history of retroactive policy changes in sectors ranging from telecommunications to retail have imposed material costs on foreign investors who arrived with optimistic assumptions.
Mexico and the Nearshoring Miscalculation
Mexico has emerged as the centerpiece of the nearshoring narrative, and the investment flows reflect that status. Proximity to the American market, the tariff architecture created by the United States-Mexico-Canada Agreement, and a large manufacturing workforce have made northern Mexico in particular a destination of extraordinary corporate interest.
What the nearshoring calculus tends to minimize is the security dimension. Significant portions of Mexico's industrial geography—including areas that have attracted substantial foreign manufacturing investment—operate in environments where organized crime exerts meaningful influence over logistics, labor markets, and local governance. This is not a peripheral concern. It is a structural feature of the operating environment that affects site selection, workforce management, and the reliability of physical infrastructure in ways that do not appear in standard market entry analyses.
Furthermore, Mexico's political trajectory under successive administrations has introduced its own category of policy risk. Energy sector nationalism, restrictions on foreign participation in strategic industries, and a governance philosophy that periodically prioritizes domestic political objectives over investor protections have created an environment where the regulatory ground can shift with limited warning.
The Second-Order Exposure Nobody Is Modeling
Perhaps the most consequential failure in current decoupling strategy is the absence of rigorous second and third-order analysis. Executives are, understandably, focused on first-order questions: Can we source this component outside China? Can we manufacture this product in a country not subject to current tariff exposure? These are legitimate questions. They are also insufficient.
The second-order questions are where genuine strategic intelligence becomes decisive. How does the country receiving our redirected investment relate to China economically? What leverage does Beijing retain over that country's government? If a conflict scenario involving Taiwan were to materialize, how would our Vietnamese or Malaysian or Thai suppliers respond to Chinese pressure? These questions are not hypothetical. They are the analytical terrain on which future supply chain resilience will actually be determined.
Third-order questions push further still. As dozens of American corporations simultaneously redirect investment toward the same alternative markets, what does that concentration do to local political economies? Does it create new points of leverage that hostile state actors can exploit? Does it generate the kind of strategic dependency—now distributed across several countries rather than one—that decoupling was intended to eliminate?
The honest answer, in most cases, is that these questions are not being asked with sufficient rigor.
What a Mature Decoupling Strategy Actually Requires
Reducing China exposure remains a legitimate strategic objective for many American corporations. The argument here is not that decoupling is misguided—it is that the execution of decoupling, as currently practiced by most firms, reflects a binary logic that is strategically immature.
A genuinely resilient approach requires several things that most corporate decoupling programs currently lack. It requires granular geopolitical intelligence about the specific countries receiving redirected investment—not country-level generalizations, but analysis of the political, security, and economic dynamics relevant to the specific industries and regions involved. It requires scenario modeling that accounts for how alternative supply chain nodes would perform under stress conditions, including conditions created by the very geopolitical tensions that motivated decoupling in the first place.
It also requires intellectual honesty about the distinction between compliance risk reduction—which decoupling often achieves effectively—and operational resilience improvement, which is a more demanding standard that current strategies frequently fail to meet.
The Strategic Imperative
The companies that will navigate the next decade of geopolitical disruption most effectively are not those that moved fastest to exit China. They are those that replaced the discipline of deep China expertise with an equally rigorous understanding of the markets absorbing their redirected investment. That kind of intelligence is not produced by standard market entry consulting. It requires the sustained, structured analysis of political and security dynamics that most corporate strategy functions are not currently equipped to perform.
Decoupling, executed thoughtlessly, is not risk management. It is risk migration—and migration, without a clear-eyed view of the destination, is simply a more expensive form of exposure.