Beyond the Hedge: Why Currency Risk Demands a Seat at the Executive Strategy Table
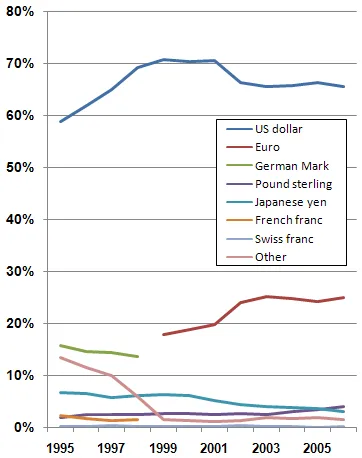
Photo: Quadell, Public domain, via Wikimedia Commons
A Finance Problem That Became a Strategy Problem
The quarterly earnings calls of American multinationals have developed a familiar ritual. Revenue growth looks strong. Margins are expanding in local-currency terms. Then the CFO mentions the impact of a stronger dollar, and the reported numbers tell a different story. Analysts adjust their models. Guidance is revised. The stock moves.
This pattern has become so common that investors have largely priced in a degree of currency drag as a cost of doing business internationally. But that normalization obscures a more serious underlying issue: many American companies are not simply experiencing currency headwinds as a recurring financial nuisance. They are making strategic decisions — about pricing, capital allocation, competitive positioning, and market entry — that are systematically disconnected from a realistic assessment of exchange rate risk.
The distinction matters enormously. A company that treats currency exposure as a finance department problem will hedge transactional risk, report the residual impact as a line-item variance, and move on. A company that treats currency risk as a strategic variable will ask fundamentally different questions: How does a sustained shift in the dollar's value relative to the Brazilian real change our competitive position against local manufacturers? If the Turkish lira depreciates another thirty percent, what happens to the purchasing power of the customer segment we built our market entry model around? How does our pricing architecture hold up under scenarios we have not yet experienced?
Those questions do not have answers that live in a treasury model. They require cross-functional engagement at the executive level.
The Structural Shifts Creating New Exposure
Understanding why currency risk has escalated as a strategic concern requires examining the macro environment that has emerged over the past several years.
The era of synchronized global monetary policy — in which major central banks broadly moved in the same direction at roughly comparable speeds — has given way to a period of significant divergence. The Federal Reserve's aggressive tightening cycle beginning in 2022 produced dollar strength that compressed earnings for American multinationals with significant emerging market revenue. Meanwhile, countries managing their own inflationary pressures, fiscal constraints, or political instability have seen their currencies behave in ways that defied short-term forecasting models.
Geopolitical realignment has added a second layer of complexity. Sanctions regimes, capital controls, and the deliberate efforts of certain economies to reduce dollar dependence in bilateral trade have created currency dynamics that are no longer purely market-driven. When a government intervenes in its exchange rate for political rather than economic reasons, the standard assumptions embedded in financial hedging models may not hold.
For American companies with revenue exposure in markets like Argentina, Nigeria, Egypt, or Turkey — all of which have experienced severe currency dislocations in recent years — the financial impact of these dynamics has been substantial. Several major consumer goods companies have reported that their reported dollar revenue from specific markets has fallen by more than half over multi-year periods, not because their local business deteriorated, but because the currency in which that business operated lost value at a pace no hedging program was designed to absorb.
What a Strategic Approach Actually Looks Like
The shift from treating currency risk as a financial management issue to treating it as a strategic one involves changes at multiple levels of the organization.
Scenario planning that includes exchange rate assumptions. Most corporate strategic planning processes model market growth, competitive dynamics, and regulatory environments across a range of scenarios. Fewer systematically incorporate exchange rate scenarios with the same rigor. A company entering a new market should model its investment thesis under a base case, an optimistic case, and a stress case — and the stress case should include a currency devaluation scenario that reflects the historical volatility of the relevant market, not just current conditions.
Pricing architecture designed for currency flexibility. Companies that lock in pricing structures in dollar terms with local distribution partners often find themselves in an untenable position when the local currency weakens. Partners cannot maintain margin at the agreed-upon dollar price, renegotiation becomes contentious, and the relationship deteriorates. Building pricing frameworks that include explicit mechanisms for currency adjustment — agreed upon before stress occurs — is a structural protection that finance alone cannot provide.
Revenue and cost currency matching at the strategic level. Where it is operationally feasible, companies can reduce net currency exposure by aligning revenue and cost currencies within a given market. A company that sources inputs locally, employs locally, and borrows locally in a given market has substantially lower net exposure to that currency than one that imports all inputs priced in dollars. These are operational and supply chain decisions, not financial ones — which is precisely why they require executive-level coordination across functions.
Competitive intelligence on currency asymmetries. When the dollar strengthens significantly against a competitor's home currency, that competitor gains a pricing advantage in shared markets. American companies should monitor these dynamics as a competitive intelligence matter, not merely a financial one. A German or South Korean competitor whose home currency has weakened relative to the dollar is not just cheaper to operate — it is strategically positioned to take market share in dollar-denominated or third-market competitive environments.
Organizational Structures That Enable Better Decisions
One of the more practical barriers to treating currency risk strategically is organizational. Treasury functions typically report to the CFO and operate with a mandate focused on managing known exposures rather than informing forward-looking strategic decisions. The analysis that would connect currency dynamics to competitive positioning, market entry economics, or customer purchasing power often falls between the remit of treasury and the remit of strategy — and in that gap, consequential decisions get made with incomplete inputs.
Leading international companies have addressed this by creating explicit mechanisms for currency risk to enter strategic planning conversations. This may take the form of a cross-functional risk committee that includes treasury, strategy, regional business leadership, and legal. It may involve embedding currency scenario analysis into the standard templates used for capital allocation decisions. The specific mechanism matters less than the underlying principle: exchange rate dynamics are a strategic variable, and the organizational process for making strategy should reflect that.
The Central Bank Mindset
Central banks think about currency not as a number to be managed but as a signal — a variable that both reflects and shapes economic conditions, competitive dynamics, and long-term positioning. They scenario plan across extreme outcomes. They think in terms of systemic exposure rather than transaction-level risk. They consider second-order effects: how a currency move affects the behavior of other actors in the system, not just the direct financial impact on their own balance sheet.
American companies operating internationally would benefit from borrowing that orientation. Not to replicate the institutional apparatus of a central bank, but to adopt the underlying discipline: taking currency seriously as a strategic force rather than a financial inconvenience, and building the cross-functional processes necessary to act on that seriousness before the next earnings call requires an explanation.